Virginia Postrel: Glamour Is Not Just Deception

“To understand glamour as no more than deception is to miss the psychological truths–and the real-world possibilities–it reveals.”

– Virginia Postrel, The Power of Glamour, p. 222 (the final page of the main text of the book)

Richard L. Evans: Every True Strength Is Gained in Struggle

“You may search all the ages for a person who has had no problems, you may look through the streets of heaven asking each one how he came there, and you will look in vain everywhere for a man morally and spiritually strong whose strength did not come to him in struggle. Do not suppose that there is a person who has never wrestled with his own success and happiness. There is no exception anywhere. Every true strength is gained in struggle.”

– Richard L. Evans

W. Keith Warner and Edward L. Kimball: Creative Stewardship

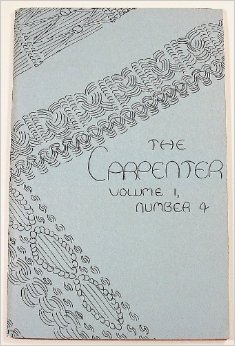
In 1969 to 1971, my father, Edward L. Kimball, was on the editorial board for a short-lived periodical: The Carpenter: Reflections of MormonLife. In the fourth and final Spring 1971 issue, he coauthored with Keith Warner the article “Creative Stewardship.” I read that article only recently (December 8, 2014). I like the message. Here is an excerpt I made, with a broad audience in mind. (He was 40 at the time, considerably younger than my current age of 54!) 


Responsibility for Accomplishment

In the Sermon on the Mount Christ said, “By their fruits ye shall know them.” (Matthew 7:20) This test, by which Christ said men may legitimately be judged, is the test of results, not of intentions.

Many of us comfort ourselves in thinking that if our purposes are right we may be excused if they go awry.

… yet the standard He offers by which we may be judged is that we bring forth good fruit. We are responsible, therefore, for effects and not merely for effort, for accomplishment and not merely activity. …

Elder Hugh B. Brown put the principle another way: “The harvest, and not the master, will accuse the slothful servant.” (Eternal Quest, Salt Lake City: Bookcraft, 1956, p. 430.)

We are familiar with the need to distinguish between faith and works: “faith without works is dead.” (James 2:26) But we often take works to mean activity rather than accomplishment, and in that sense works without results are also dead.

Our concern must be not only with the letter, but also the spirit; not only with the work, but also the fruits of the harvest. Our obligation is not merely to try, but to help the cause succeed. We can have obtained some personal growth by making an effort, even though our efforts are otherwise unfruitful, but for the sake of our community as well as ourselves we must also be effective in the long run. 

Responsibility for Initiative

… It is not unusual for us to acknowledge full responsibility for our own lives and major responsibility for the welfare of our own families and small groups of associates, but when we move beyond these to communities the size of our ward or town, and to the state or nation, most of us begin to feel that we are out of our depth, and that the problems are to be solved by someone else: the leaders, the system—somebody, but not us.

… Each must take responsibility for taking action, whether in the leadership roles to which he may have been called, or in his capacity as helpful follower, or as individual upon whom ultimate responsibility falls to be a creative steward …

The New Republican Majority Should Keep Doug Elmendorf as Director of the Congressional Budget Office

As Diogenes dramatized with his lamp, it is not easy finding an honest man. That is especially true when it comes to honesty in the face of strong political pressures. Doug Elmendorf is that rarity. If he is willing to continue as Director of the Congressional Budget Office (CBO), where honesty is especially needed, the new Republican majority would be well-advised to keep him on. They should remember that it was the CBO under Doug that pointed out what a budget-buster an early incarnation of Obamacare was. (Of course the final version was not cheap either–something the CBO under Doug also pointed out. You can see what I have to say about Obamacare here.) And it was the CBO under Doug that gave the estimate that raising the minimum wage as much as some proposed would cost half a million jobs, when the party line among many Democrats is that raising the minimum wage won’t cost any jobs at all. (You can see what I have posted so far about the minimum wage here: 1,2,3,4. I definitely lean against a higher minimum wage, but I am still debating all of the issues in my mind.) 

David Lawder makes the same case in the Reuters article “Republicans weigh big changes at U.S. budget referee agency.” One of the key issues is “dynamic scoring.” Dynamic scoring is when the changes to tax revenue induced by changes in economic behavior are included in calculations–an area where impartiality in doing the calculations is especially important because of the judgment calls that need to be made. The CBO has already done some dynamic scoring in unofficial estimates. Here are some key excerpts from David Lawder’s reporting:

The budget math used under dynamic scoring has long been a goal for Republican lawmakers, including the incoming chairman of the House Budget Committee, Representative Tom Price, and the current chairman, Paul Ryan, who next month will take over the tax-writing House Ways and Means Committee. …

“What we’re simply striving for is accuracy in score keeping,” Ryan told Reuters in a recent interview. “We know for a fact that it is not accurate or prudent to ignore the effects of economic growth on policies we make in Congress.” …

“I’ve always said that Doug Elmendorf has done an extremely good job at CBO,” Price said. “My complaint, my concern about CBO is not about the individual at the lead of CBO, my concern is the rules under which they operate.” …

… several prominent conservative economists have backed Elmendorf, arguing that Republicans would gain more credibility by keeping the former Clinton administration economist. …

“If you’re going to go with dynamic scoring, Elmendorf is a great guy to implement that,” said Michael Strain, deputy director of economic policy studies at the conservative American Enterprise Institute. “It would be harder to accuse Republicans of putting their thumb on the scale” if he stays.

To everything said above about dynamic scoring, let me add that I think Doug Elmendorf is the right person to implement disciplined capital budgeting to the CBO. I have in mind the approach I advocated when I visited the CBO this past May. (See my post “Capital Budgeting: The Powerpoint File.)

I know Doug well. Doug is a Harvard PhD classmate of mine, a coauthor on "Taxation of Labor Income and the Demand for Risky Assets” and a friend. So I can’t claim to be unbiased. But everything I am saying about Doug Elmendorf, others are saying as well.  

Bleg: It may be important to write again on this topic. So I would be grateful for links and information relevant to the argument for keeping Doug as Director of the CBO.

In Defense of Clay Christensen: Even the ‘Nicest Man Ever to Lecture’ at Harvard Can’t Innovate without Upsetting a Few People

Here is a link to my 57th column on Quartz: "In Defense of Clay Christensen: Even the ‘Nicest Man Ever to Lecture’ at Harvard Can’t Innovate without Upsetting a few people.“

I wrote a version of this first as a blog post. I am delighted that my new editor at Quartz, Paul Smalera, liked it enough to publish it in Quartz. (My previous editor, Mitra Kalita, is now overseeing key aspects of Quartz’s global expansion.)

By the way, since I am blogging through Clay’s books (as I have been blogging through John Stuart Mill's On Liberty) I have a virtual sub-blog on Clay Christensen:

http://blog.supplysideliberal.com/tagged/clay

In the column, I give my take on Clay’s theory, which I think is important for economists to understand. Here is a teaser:

My views on Clay as a thinker come from reading six of Clay’s books this year …

As an economist, I found them fascinating. One of the hottest areas of economics in the last twenty years has been the border between economics and psychology. One basic idea at that intersection is that people have limitations in their ability to process information and make decisions. This idea that cognition is finite is a key issue in macroeconomics, as Noah Smith and I wrote about in “The Shakeup at the Minneapolis Fed and the Battle for the Soul of Macroeconomics—Again.” But the idea of finite cognition also matters a lot for businesses. Some decisions are hard even for people who spend their careers making those kinds of decisions, and the support of teams of experts.

Clay, in the management theory he has developed with various coauthors, identifies one key factor in how hard a decision is for a generally well-run business …

Alexander Trentin: "Japan, It's Time to Finally Overthrow Cash!"

blog.supplysideliberal.com tumblr_inline_ngh2txCVj91r57lmx.png

Link to the article on the Finanz und Wirtschaft website

Some of the best reporting ever on my proposal to eliminate the zero lower bound is in German. I am delighted by Alexander Trentin’s article “Japaner, shafft endlich das Bargeld ab” on the Finanz und Wirtschaft site. (“Finanz und Wirtschaft” means “Finance and Economics.”) And I am very grateful for his permission to publish an English translation here.

This article is closely related to my column “Righting Rogoff on Japan’s Monetary Policy,” but I recommend reading this one first. Also, I can’t fail to mention the news this week that the Swiss National Bank has gone to negative interest rates. I wrote about that in my latest Quartz column: “The Swiss are now at a negative interest rate due to the Russian ruble collapse.”

Below the row of stars is my translation of Alexander Trentin’s words, with the help of my college German, Google translate, and my knowledge of the substance. Based on substance, I translated “abschaffen” as “overthrow” instead of “abolish” because I don’t advocate abolishing cash, only demoting it. Similarly, I translated “solange es den Yen noch als Bargeld gibt” to “as long as cash still rules in Japan” instead of “as long as there is yen as cash” for the same reason. The Tokugawa Shogunate was overthrown with the slogan “Honor the Emperor and expel the barbarians!" The right slogan for Japan now is "Honor the electronic yen and end the lost decades!”


Has the Bank of Japan really done everything possible to create inflation? No, says a US economist, as long as cash still rules in Japan.

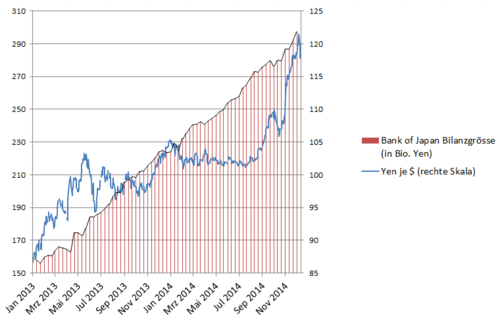
The Bank of Japan wants inflation. To that end, it expanded its bond purchase program (QE) in late October. The currency markets are impressed. The central bank balance grows with those purchases, while the yen’s exchange rate vis a vis the dollar weakens:

Source: Bloomberg. Red stripes, left scale: BOJ balances in trillions of yen. Jagged blue line, right scale: Yen per US dollar.

Source: Bloomberg. Red stripes, left scale: BOJ balances in trillions of yen. Jagged blue line, right scale: Yen per US dollar.

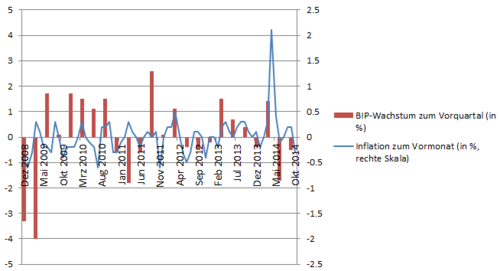
But stimulating growth by stimulating inflation is much more difficult than devaluing the currency. In the last two quarters, the economy contracted. And in October, prices fell again. The temporarily high inflation of 2% in April was achieved by increasing the consumption tax. Now, the decline in oil prices has lowered inflation expectations in Japan.

Source: Bloomberg. Red bars, left scale: quarterly growth in GDP. Blue line, right scale: inflation in the previous month.

Source: Bloomberg. Red bars, left scale: quarterly growth in GDP. Blue line, right scale: inflation in the previous month.

The consensus among market analysts is that the Bank of Japan has fulfilled its task. And it has been expanding its QE program. Harvard economist Kenneth Rogoff argued recently that structural reform is the only hope for Japan’s economy, because the Bank of Japan has done all it can: that is the only way Japan can get out of deflation and low growth.

But is this really true? For Miles Kimball, a professor at the University of Michigan, it isn’t true that the Bank of Japan has really tried everything. Because the Japanese could cut interest rates. They are already at zero, but Kimball is one of the economists who advocate electronic money instead of paper money to make it possible to charge negative interest rates. If there were no more cash, you couldn’t use paper money to save yourself from negative interest rates in your bank account–negative interest rates that have already been introduced in certain German banks for business customers. On Twitter, Miles Kimball writes:

The Japanese are interested

He presented his view last year at the Bank of Japan and Japan’s Ministry of Finance. And according to Kimball’s website, the Central Bank and the Ministry of Finance were “interested” in his proposal.

In Kimball’s proposal, paper currency would continue to exist, but prices would be expressed in units of electronic money. There would be a time-varying exchange rate between electronic money and paper money. “We wouldn’t have to worry about [central banks] ever again seeming relatively powerless in the face of a long slump" Kimball writes in a column.

Absolute price stability is possible

But Kimball is no fan of inflation who wants to make the money in our pockets or in our bank accounts worth continually less and less. On the contrary, he argues that the possibility of negative interest rates makes the generally accepted inflation target of 2% unnecessary. An inflation target of 0%–that is, absolute price stability–would then be possible.

His reasoning: Central banks want an inflation rate of 2% so they have room to push the real interest rate low enough. The real interest rate is the nominal interest rate minus the inflation rate. For investment decisions, the real interest rate is crucial. If the nominal interest rate can’t go below 0%, an inflation rate of 2% is needed to make a real interest rate of -2% possible. However, if the nominal interest rate can be negative, then a central bank no longer needs to get the leeway for negative real interest rates from a positive rate of inflation.

"The benefits of true price stability alone would easily make up for any inconvenience of [electronic money,]” believes Kimball. If the Bank of Japan cannot generate persistent inflation even after continued huge bond purchases, maybe Japan will be the first nation to overthrow paper money.

John Stuart Mill on Being Offended at Other People's Opinions or Private Conduct

John Stuart Mill was a Utilitarian. A thoroughgoing Utilitarian has to confront the unpalatability of counting into Social Welfare calculations the utility people get from knowing that other people are off doing what they want other people to do. Is the pain a homophobe feels at contemplating married gay couples to be deducted from Social Welfare? I consider this question still unresolved. As Dan Benjamin, Ori Heffetz, Nichole Szembrot and I discuss in “Beyond Happiness and Satisfaction: Toward Well-Being Indices Based on Stated Preference,” some philosophers and social scientists suggest basing one’s social welfare calculations on “laundered” preferences that leave out, say, racist attitudes.

The alternative that I am drawn to is to deconstruct “dirty” preferences into the “clean” preferences they are composed of. For example, resentment at another race may stem from a desire to be respected oneself, plus a false belief that the only way to be respected is if some group is clearly put on a lower plane–and the ethical judgment that using such means is OK. The desire to be respected is itself a legitimate desire, but that legitimate desire is poisoned by a belief about the cause of one’s troubles and a reprehensible strategy for achieving that desire. In other words, racism or homophobia are bad, but is it (a) the underlying desires that are bad, (b) the beliefs accompanying those desires, or (c ) the willingness to harm others (perhaps through government restrictions) implicit in homophobia or racism.

In On Liberty, Chapter IV, “Of the Limits to the Authority of Society over the Individual” paragraph 12, John Stuart Mill effectively downplays the problem of direct preferences over others’ conduct or opinions by arguing that preferences over others’ self-regarding conduct or others’ opinions tend to be weak compared to the strength of preferences over one’s own conduct or opinions:

There are many who consider as an injury to themselves any conduct which they have a distaste for, and resent it as an outrage to their feelings; as a religious bigot, when charged with disregarding the religious feelings of others, has been known to retort that they disregard his feelings, by persisting in their abominable worship or creed. But there is no parity between the feeling of a person for his own opinion, and the feeling of another who is offended at his holding it; no more than between the desire of a thief to take a purse, and the desire of the right owner to keep it. 

I love the last sentence so much that I made it into a quotation post in its own right yesterday:

… there is no parity between the feeling of a person for his own opinion, and the feeling of another who is offended at his holding it; no more than between the desire of a thief to take a purse, and the desire of the right owner to keep it. 

What John doesn’t address is what to do in a case where, say, I have only a mild preference over my own conduct or opinion, and for some reason you have a strong preference over my conduct or opinion. In many cases, some sort of modest side payment can usually take care of such cases, precisely because of that imbalance of preferences. But who makes a side payment to whom depends on the assignment of initial rights, which is the key question here.  

One way to deal with the theoretical issue is to define “other-regarding” conduct (including holding certain offensive opinions) as conduct that others care as much or more about than the one doing the conduct (or holding the opinion). But this is an invitation to those who dislike some conduct (or opinion) to get themselves worked up enough that their indignation is big enough to get counted.

Here I have in mind Ed Glaeser’s “The Political Economy of Hatred.” I liked the working paper version of this paper because of its model of a psychological production function for hatred in the working paper version of this paper. In the published version, that was replaced by a more rational model of hatred induction. The shift can be seen in the difference between the abstract of the working paper and the abstract of the published version. Here is the abstract of the working paper:

What determines the intensity and objects of hatred? Hatred forms when people believe that out-groups are responsible for past and future crimes, but the reality of past crimes has little to do with the level of hatred. Instead, hatred is the result of an equilibrium where politicians supply stories of past atrocities in order to discredit the opposition and consumers listen to them. The supply of hatred is a function of the degree to which minorities gain or lose from particular party platforms, and as such, groups that are particularly poor or rich are likely to be hated. Strong constitutions that limit the policy space and ban specific anti-minority policies will limit hate. The demand for hatred falls if consumers interact regularly with the hated group, unless their interactions are primarily abusive. The power of hatred is so strong that opponents of hatred motivate their supporters by hating the haters.

By contrast, here is the abstract of the published version:

This paper develops a model of the interaction between the supply of hate-creating stories from politicians and the willingness of voters to listen to hatred. Hatred is fostered with stories of an out-group’s crimes, but the impact of these stories comes from repetition not truth. Hate-creating stories are supplied by politicians when such actions help to discredit opponents whose policies benefit an out-group. Egalitarians foment hatred against rich minorities; opponents of re-distribution build hatred against poor minorities. Hatred relies on people accepting, rather than investigating, hate-creating stories. Hatred declines when there is private incentive to learn the truth. Increased economic interactions with a minority group may provide that incentive. This framework is used to illuminate the evolution of anti-Black hatred in the United States South, episodes of anti-Semitism in Europe, and the recent surge of anti-Americanism in the Arab world. 

Either way, strong feeling ginned up by political entrepreneurship does not seem to me like something that should be respected in the social welfare function. 

All of these issues deserve much more discussion. 

“… there is no parity between the feeling of a person for his own opinion, and the feeling of another who is offended at his holding it; no more than between the desire of a thief to take a purse, and the desire of the right owner to keep it.”
— John Stuart Mill

Joe Weisenthal on Willem Buiter's List of 3 Ways to Eliminate the Zero Lower Bound →

What Willem Buiter has written on eliminating the zero lower bound is not always the easiest reading. So Joe Weisenthal’s May 9, 2012 summary linked above is useful. 

For more links on Willem Buiter and others who played a role in the eventual end of the zero lower bound, see the section on History of Thought and Economics History in my bibliographic post “How and Why to Eliminate the Zero Lower Bound: A Reader’s Guide.

Thanks to Ellie Kesselman, for the trail that lead me to Joe's Business Insider article. 

The Swiss National Bank Means Business with Its Negative Rates

This is a link to my 56th column on Quartz: “The Swiss are now at a negative interest rate due to the Russian ruble collapse.” I kept something closer to my working title as the title of this companion post, and as what I plan for the long-run title.

This column is in honor of all the amazing people I met at the Swiss National Bank.

Update December 19: Paul Krugman links to my column as a news source in his column “Switzerland and the Inflation Hawks.” The link is on the words “charging banks." 

“… simplistic nationalism is every bit as ugly as racism, and in exactly the same way. Encouraging people to “buy American” is no different in principle from encouraging people to “buy white.””

– Steven E. Landsburg, Fair Play, p. 15

My Advice to Qatar: Make Math Education a Research Grand Challenge

blog.supplysideliberal.com tumblr_inline_ng6u60tmt51r57lmx.png

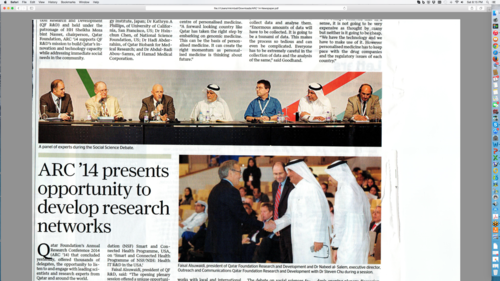
I was invited to be on a social science panel for the Qatar Foundation’s 2014 Annual Research Conference in Doha. While there, I took the opportunity to give a talk on “Breaking Through the Zero Lower Bound” at Texas A&M’s Doha campus, moderated by Dr Khalid Rashid Alkhater, director of research and monetary policy and member of the Monetary Policy Committee and the Investment Committee at the Qatar Central Bank. And I had a chance to see Doha. (You can see the best of the photos I took here and here.) 

The Annual Research Conference itself was quite interesting. Except for the Social Sciences, it was organized around four “Research Grand Challenges”: Water Security, Energy Security, Cyber Security and Integrated Health Care. In addition, there is an overarching goal of making Qatar into a “Knowledge Economy.” The panel I was on (see the picture of me and the other panelists above) was on the second day of the conference. On the first day of the conference, I sent an email to several of the other panelists and others I met suggesting that the Qatar Foundation make Math Education its fifth Research Grand Challenge. Here is a lightly edited version of that email:

I promised each of you to send links to the two articles I wrote for Quartz (a relatively new online international business magazine started by the Atlantic Company) about math education:

There’s One Key Difference Between Kids Who Excel at Math and Those Who Don’t

How to Turn Every Child into a “Math Person”

These articles had a large number of pageviews, indicating a great deal of concern about math education.I think it would be both attainable and extremely valuable for the Qatar Foundation to make it a key goal to be the number one center for research and knowledge about math education in the world. Gathering that knowledge, and then implementing it in Qatar’s schools would have a bigger bang for the buck than anything else in achieving the broader goal of fostering a knowledge economy in Qatar. And having such a center would be a great benefit to the rest of the world as well.  Because schools of education in the US and likely many other prestigious countries are often quite politicized, it is crucial to bring into the effort of figuring out the best way to do math education experts whose home is in other fields besides education, as well as some of the best education scholars.   Along these interdisciplinary lines, one of the best education thinkers is actually a renowned professor at Harvard Business School: Clay Christensen. (He has many times won the top award in the world for a business strategist.) With his coauthors, he has written a pair of excellent books on the transformation ofeducation that is now underway because of high-powered computing–#4 and #5 in this list:
I think all of the other stakeholders in the Qatar Foundation in the natural sciences will easily see the value of an emphasis on figuring out how to do math education well–something most advanced countries do not do.   In terms of tracking the achievement of the goal of math education, the single most important measure would be to ask representative samples of kids “Do you love math.” Success would be 90% of students honestly saying “Yes.”  If almost all of Qatar’s children loved math, the knowledge economy would follow as day follows night. 

The question for the panel discussion was particularly about survey data collection for Qatar. In my initial statement, I began by mentioning the importance of measuring national well being, but said that for the goal of becoming a knowledge economy, measuring some other intermediate goals made sense. I laid out for those attending the panel discussion the idea of making Math Education a fifth Research Grand Challenge, identifying and implementing best practice for math education, including the use of new technologies. I urged that Qatar should set a goal of making math education in Qatar better than math education in any other nation, saying that was unfortunately easy because the standards for math education are low. As in my email, I said that if I could choose one survey question to monitor the progress of this effort, it would be to ask kids “How do you feel about math.” If 90% of kids said that they loved math that would be success: in particular, it would augur good things for Qatar’s hopes of becoming a knowledge economy.   

In the discussion that followed, I had to defend the choice of math education as a focus. Of course there are many other issues in education, but I maintain that because doing math education right is the hardest, solving that would put Qatar in a great position to improve education more generally. For example, coding (what we called “computer programming” when I was young) uses much of the same type of thinking as mathematics, but it is probably easier to motivate kids to be excited about computer programming than it is to motivate them to be excited about math.  (Improving foreign language education–which in much of the world is first and foremost learning English–is a fascinating issue, and one that I studied in the course of getting my MA in Linguistics. Like math education, I think foreign language education can be dramatically improved. But I should save my thoughts on that for another post.)   There were other things I didn’t have time to say in the panel discussion, but said in conversations beforehand and afterwards. In line with the thinking of Clay Christensen and his coauthors, I argued that the potential of technology is in making it possible to have a division of labor between

  • teachers who have a deep knowledge of the subject matter of economics, who record online lectures and help design computer programs that teach mathematics (the teacher-at-a-distance) and
  • teachers who are expert at motivating students (the coach-on-the-spot).  

It is wonderful but rare to find a single teacher who combines deep mathematical knowledge and brilliance at motivating students; it is much easier to find someone who has one of these skills. I actually think coaching talent–the ability to motivate–is relatively abundant. But the ability to instill enthusiasm needs to be teamed up with a good teacher-at-a-distance with the deep subject matter knowledge.

In any case, this line of thought gives me some confidence that dramatically better programs of math education are possible. A research center in Qatar focusing on math education that brought in the top experts from around the world to debate one another and generate new ideas could dramatically improve the world’s knowledge of how to do math education. I don’t claim to know all the answers about math education. But I know enough to be confident that what is possible for math education is far beyond what is currently done. In particular, any system of math education that leads to half of all kids hating math at the end, is far, far below the possibility frontier.  

The goal of being the best in the world at something has a powerful motivating force. There is honor to be had for any nation that takes seriously the challenge of fulfilling the potential of math education. And for Qatar to do so might transform not only Qatar, but the whole Arab world, allowing the Arab world to reclaim the preeminence in mathematics that was one of the hallmarks of the Arab world’s golden age. (There is a reason so many key words in math, such as “algebra,” “algorithm,” “cipher,” and perhaps even “average” come from Arabic.) 

“Behold my son, with how little wisdom the world is governed.”

– Axel Oxenstierna, Swedish statemen who lived 1583 – 1654, via Matt Miller’s book The Tyranny of Dead Ideas, p. 228, who offers this interpretation: “In one sense, the Swede was simply saying, ‘Look at what idiots are running things!’ In another sense, though, he was offering a deeper observation about how small a quantity of wise governance is actually required to keep the human enterprise on track.

Righting Rogoff on Japan's Monetary Policy

Here is a link to my 55th column on Quartz: “Righting Rogoff on Japan’s monetary policy.”

This column is meant to back up my tweet:

Ken Rogoff is wrong when he says the BOJ’s Kuroda has done “whatever it takes” monetary policy for Japan: http://www.project-syndicate.org/commentary/japan-slow-economic-growth-by-kenneth-rogoff-2014-12…

One other note: Ken sent a nice reply to the email I sent him about my work on eliminating the zero lower bound, soon after I sent it. 

Update December 19, 2014: Although the main point of my column is to emphasize the importance of putting negative paper currency interest rates in the monetary policy toolkit now rather than a decade or two from now (with particular urgency for the European Central Bank and the Bank of Japan), I know that for many readers, the reprise of the Spring 2013 media furor about Carmen Reinhart and Ken Rogoff’s work is equally salient. Personally, I believe eliminating the zero lower bound is much more important as whether debt lowers economic growth even when it doesn’t cause a debt crisis, but the issue of debt and growth does need to be addressed as well. 

I had a chance to read Ken Rogoff’s and October 2013 FAQ http://scholar.harvard.edu/rogoff/publications/faq-herndon-ash-and-pollins-critique. Substantively, I think this is a good response to the Thomas Herndon, Michael Ash and Robert Pollin paper (linked there) that started the media furor in Spring 2013. But my own substantive concerns are not those. They are the concerns that Yichuan Wang and I detail in our two Quartz columns and two other posts on Reinhart and Rogoff’s work:

In my view, these posts by Yichuan Wang and me are a good example of how, in Clay Christensen’s terms, the disruptive innovation of the economics blogosphere is beginning to move upscale and challenge traditional economics outlets such as working papers and journal articles.

I hope that, taken as a whole, what I write on my blog puts things in the context of the literature, and–through links–gives the kinds of references that are rightly considered important for academic work. In any case, for me the major source of the not inconsiderable number of references I have had in my academically published work come from other people telling me about work related to my own. The same thing happens online. I deeply appreciate the many links people send me in tweets and in more private communications. 

Although it is natural for an individual blog post to be be much less complete than a working paper or journal article, I hope to achieve a reasonable balance between breadth and depth in this blog as a whole. And of course, the relative difficulty of putting mathematical equations in Tumblr means I will choose the working paper format once the number of equations needed to make a point exceeds a certain threshold. 

To repeat, although Thomas Herndon, Michael Ash and Robert Pollin’s paper definitely piqued my interest and Yichuan’s interest and so led to our analysis of Carmen Reinhart and Ken Rogoff’s postwar data, I am critical of the substance of Carmen and Ken’s work based on my work with Yichuan, not based on the work of Thomas Herndon, Michael Ash and Robert Pollin.

In relation to our own critique of Carmen and Ken’s work, let me make three substantive points:

  1. Nonlinearity. In our last piece on Reinhart and Rogoff’s work, http://blog.supplysideliberal.com/post/55484991854/quartz-25-examining-the-entrails-is-there-any
  2. Yichuan and I look nonlinearly at how different levels of debt are related to growth beyond what one would expect from looking at past growth alone. It would be nice to have more evidence total, but on its face, the hint has a higher growth rate after controlling for past growth at a 90% debt to GDP ratio than at a 50% debt to GDP ratio. And we do suggest that what little evidence there is in the data suggests that, say, 130% debt to GDP ratio is associated with lower growth beyond what would be predicted by past growth than a 90% debt to GDP ratio, though a 130% debt to GDP ratio and a 50% debt to GDP ratio give about the same level of growth beyond what would be predicted by past growth alone. On theoretical grounds, it seems plausible to me, though far from an open-and-shut case that high enough debt levels would cause problems for economics growth. That thinking has led me to argue persistently that monetary stimulus is better than fiscal stimulus because it does not raise national debt. See for example my post “Monetary vs. Fiscal Policy: Expansionary Monetary Policy Does Not Raise the Budget Deficit.”But exactly how high that is matters a lot when people can’t be convinced of the virtues of negative interest rates so that fiscal stimulus remains an issue. I consider the nonlinear smoother result that (given what power there is in the postwar data set) the line is the same at a 130% debt to GDP ratio as at a 50% debt to GDP ratio, even after correcting for “illusory growth” on the part of Ireland and Greece as painting a considerably different picture than someone would get from reading Carmen Reinhart and Ken Rogoff’s, or Carmen Reinhart, Vincent Reinhart and Ken Rogoff’s work.
  3. Is controlling for past GDP growth appropriate? In my view, yes. I consider the past income growth controls important because countries that are generally messed up are likely to have both high debt and low growth. That doesn’t mean the high debt causes low growth. Most of the discussion has focused on reverse causality, but I consider the positive correlation across many dimensions of bad policy to be another big issue. I worry that the past income controls would make it hard to detect whether or not debt overhangs are followed by long-lasting low-growth periods, as Carmen, Vincent and Ken argue. But without some other way to control for the many, many other possible bad policies besides debt (which goes beyond the kind of growth accounting regressions that Ken’s FAQ document points to as strong evidence in favor of the view that debt might slow growth) this seems to me to point toward genuine empirical agnosticism about whether debt lowers growth as the right conclusion. (Theoretical arguments are a different matter.)
  4. Does the prewar data strongly bolster the case the debt slows growth?  Here, it depends on what the question means. The prewar data were not as readily available as the postwar data, so Yichuan and I did not analyze them. And so I don’t know what they say, once subjected to the kind of empirical exercises I would like to subject them to. I would love to see an analysis like the one the Yichuan and I did on the postwar data applied to the prewar data. That said, the prewar data may answer the question of whether a given debt level lowered growth under the gold standard, or with prewar institutions that were weaker than current institutions. So I have my doubts about how much guidance it can give to policy now. Monetary policy in particular, had advanced dramatically since the pre-World War II era, even before the ongoing revolution against the paper currency standard. 

Did Carmen and Ken overstate their case? 

While I feel confident that Yichuan’s and my substantive critique has not been adequately addressed, I am much less confident about claims I made in 

“Righting Rogoff on Japan’s monetary policy”

 about how policy-makers interpreted Carmen and Ken’s work (and how they could have been expected to have interpreted it, given what was written).

Ken’s FAQ document points to the 2010 Voxeu article “Debt and Growth Revisited” as something that could have provided more balance to policy makers in interpreting Carmen (and Vincent) and Ken’s work. Because policymakers might be more likely to read a Voxeu article than an academic paper, this Voxeu piece is an important touchstone for whether Carmen and Ken overstated the strength of the empirical evidence in favor of the idea that high public debt slows down growth in the range that was relevant to policy in the last few years.

The issue I have with the Voxeu article “Debt and Growth Revisited” is that it never mentions the fact that the normal standard of establishing causality in economics is to find a good instrument, or some other source of exogeneity or quasi-exogeneity. In other words, the inherent difficulty of establishing causality in this kind of data is never mentioned. Here is how strongly Carmen and Ken suggest in their Voxeu article “Debt and Growth Revisited” that there is causal evidence despite the highly endogenous nature of the data:

Debt-to-growth: A unilateral causal pattern from growth to debt, however, does not accord with the evidence. Public debt surges are associated with a higher incidence of debt crises.9 This temporal pattern is analysed in Reinhart and Rogoff (2010b) and in the accompanying country-by-country analyses cited therein. In the current context, even a cursory reading of the recent turmoil in Greece and other European countries can be importantly traced to the adverse impacts of high levels of government debt (or potentially guaranteed debt) on county risk and economic outcomes. At a very basic level, a high public debt burden implies higher future taxes (inflation is also a tax) or lower future government spending, if the government is expected to repay its debts.

There is scant evidence to suggest that high debt has little impact on growth. Kumar and Woo (2010) highlight in their cross-country findings that debt levels have negative consequences for subsequent growth, even after controlling for other standard determinants in growth equations. For emerging markets, an older literature on the debt overhang of the 1980s frequently addresses this theme. …

… We have presented evidence – in a multi-country sample spanning about two centuries – suggesting that high levels of debt dampen growth.

I appreciate the note of uncertainty in the sentence  

Perhaps soaring US debt levels will not prove to be a drag on growth in the decades to come.  

But I feel that for the typical policy maker reading the Voxeu article, this note of uncertainty is largely cancelled out by the next sentence: 

However, if history is any guide, that is a risky proposition and over-reliance on US exceptionalism may only prove to be one more example of the “This Time is Different” syndrome.

The phrase “if history is any guide” phrase in particular suggests that the historical evidence gives some clear guidance, and the sentence as a whole points to an interpretation of “Perhaps soaring US debt levels will not prove a drag on growth in the decades to come” as simply making a bow toward random variation around a regression line rather than expressing any uncertainty about what the causal regression line for the effect of debt on growth says before other random factors are added in.

In any case, saying “Perhaps soaring US debt levels will not prove to be a drag on growth in the decades to come” is not the same as if Carmen and Ken had said

Of course further research could overturn the suggestion we find in the evidence that high debt lowers growth, and there are always many difficulties with interpreting historical evidence of this kind.

Of course, there is always the possibility that Carmen and Ken said almost exactly that, in a forum that most policy makers would have noticed, but one that Idid not notice. (My own reading is ridiculously far from comprehensive.) If so, I would love to get a link to it. Ideally, I would like to see the main text of Ken's FAQ document collect in its main text all the details (including of course venue or outlet and date) about all the strongest caveats and cautions against overreading that Carmen, Vincent and Ken wrote about their work. 

One extremely important note that the FAQ document does have is this quotation from Reinhart, Reinhart, and Rogoff (2012), “Public Debt Overhangs: Advanced-Economy Episodes since 1800.” (Journal of Economic Perspectives, 26(3)): 

This paper should not be interpreted as a manifesto for rapid public debt deleveraging exclusively via fiscal austerity in an environment of high unemployment. Our review of historical experience also highlights that, apart from outcomes of full or selective default on public debt, there are other strategies to address public debt overhang, including debt restructuring and a plethora of debt conversions (voluntary and otherwise). The pathway to containing and reducing public debt will require a change that is sustained over the middle and the long term. However, the evidence, as we read it, casts doubt on the view that soaring government debt does not matter when markets (and official players, notably central banks) seem willing to absorb it at low interest rates – as is the case for now.”

This suggests to me that Paul Krugman went overboard in his criticism of Carmen and Ken–at least before he backed off somewhat. I am not up on all the details, but it is my understanding that some of Paul Krugman’s stronger criticisms against Carmen and Ken in terms of providing intellectual backing for austerity might have been better leveled against other influential economists, such as Alberto Alesina. But I would need a lot of help to know whether such criticisms were even appropriate for other influential economists such as Alberto. For the record, the current Wikipedia article on Alberto Alesina says:

In October 2009 Alesina and Silvia Ardagna published Large Changes in Fiscal Policy: Taxes Versus Spending,[3] a much-cited academic paper aimed at showing that fiscal austerity measures did not hurt economies, and actually helped their recovery. In 2010 the paper Growth in a Time of Debt by Carmen Reinhart and Kenneth Rogoff) was published and widely accepted, setting the stage for the wave of fiscal austerity that swept Europe during the Great Recession. In April 2013 some analysts at the IMF and the Roosevelt Institute found the Reinhart-Rogoff paper flawed. On June 6, 2013 U.S. economist and 2008 Nobel laureatePaul Krugman published How the Case for Austerity Has Crumbled[4] in The New York Review of Books, noting how influential these articles have been with policymakers, describing the paper by the ‘Bocconi Boys’ Alesina and Ardagna (from the name of their Italian alma mater) as “a full frontal assault on the Keynesian proposition that cutting spending in a weak economy produces further weakness”, arguing the reverse.

Thus, Wikipedia conflates Carmen and Ken’s views with those of Alberto Alesina and Silvia Ardagna.

But just as Carmen and Ken’s views should not be conflated with Alberto and Silvia’s views, neither should my views be conflated with Paul Krugman’s. Soon after Thomas Herndon, Michael Ash and Robert Pollin’s paper came out, I wrote in Quartz:

Unlike what many politicians would do in similar circumstances, Reinhart and Rogoff have been forthright in admitting their errors. (See Chris Cook’s Financial Times post, “Reinhart and Rogoff Recrunch the Numbers.”) They also used their response to put forward their best argument that correcting the errors does not change their bottom line. Given the number of bloggers arguing the opposite case—that Reinhart and Rogoff’s bottom line has been destroyed—it is actually helpful for them to make their case in what has become an adversarial situation, despite their self-justifying motivation for doing so. And though I see a self-justifying motivation, I find it credible that Reinhart and Rogoff’s original error did not arise from political motivations, since as they note in their response, of their two major claims—(1) debt hurts growth and (2) economic slumps typically last a long time after a financial crisis—the claim that debt hurts growth is congenial to Republicans, while the claim that it is normal for slumps to last a long time after a financial crisis is congenial to Democrats.

The results from the fairly straightforward data analysis that Yichuan and I did made me somewhat less sympathetic to Carmen and Ken. Nevertheless, I think they spoke and wrote in good faith. Errors of omission are a different issue, and there we all stand condemned, in a hundred different directions for each of us. 

It is from the perspective that we all stand condemned for errors of omission of one type or another, that I hope my words in “Righting Rogoff on Japan’s monetary policy” are taken. I also urge you to distinguish carefully between simply reportingone side of the Spring 2013 debate about Reinhart and Rogoff’s work, and things I say on my own behalf: principally that Ken does not challenge policy-maker conventional wisdom as much as I would like to see. 

Carmen and Ken literally did not have time enough to defend themselves adequately back in Spring 2013. Now that the dust has cleared, I would be glad to see them do more to tell their side of the story. 

This update is my effort to make up for some of my own errors of omission when I wrote “Righting Rogoff on Japan’s monetary policy.” In particular, I thought wrestling with Ken’s FAQ document was the least I could do to give a little more voice to Carmen and Ken’s side of the story. (To the extent that you were persuaded by Thomas Herndon, Michael Ash and Robert Pollin’s paper, or were persuaded by unjustified accusations of bad faith on Carmen and Ken’s part, you should take a close look at that FAQ document.) As always for my columns, this update in the companion post will become part of the permanent record for this column 30 days or so after initial publication on Quartz, when I am contractually allowed to bring the column home to supplysideliberal.com.
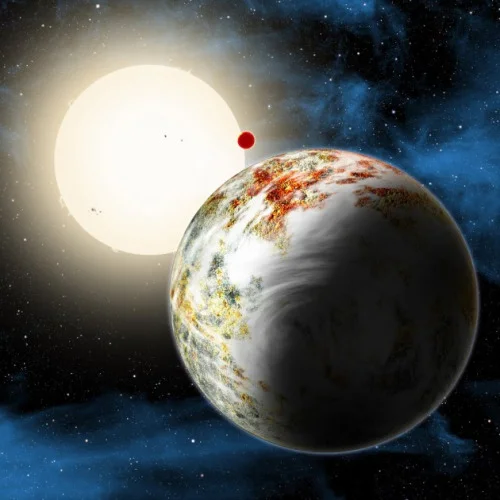
I like this illustration I am reblogging from the smithsonian Tumblog. It is accompanied by this note:

Astronomers at Harvard-Smithsonian Center for Astrophysics find new “mega-Earth”. 

“This is the Godzilla of Earths!” - CfA researche…

I like this illustration I am reblogging from the smithsonian Tumblog. It is accompanied by this note:

Astronomers at Harvard-Smithsonian Center for Astrophysics find new “mega-Earth”. 

“This is the Godzilla of Earths!” - CfA researcher Dimitar Sasselov, director of the Harvard Origins of Life initiative"

Read more at Smithsonian Science. 

Like reblogged posts from econlolcats, this post is also intended as a harbinger of a Quartz column I expect to appear today: my response to Ken Rogoff's Project Syndicate opinion piece “Can Japan Reboot? The working title is "Righting Rogoff on Japan’s Monetary Policy."